Market, Limit, and Stop Orders: Choose How to Enter and Exit
Understand what each order controls, how a trigger differs from a fill, and why a stop order cannot guarantee your exit price.
In brief
- Takeaway
- Market seeks execution; limit sets a price boundary; stop waits for a trigger.
- How to use it
- A stop-market can slip. A stop-limit can fail to exit.
- Check first
- A candle closing above a level and a stop triggering during the candle are different events.
Before you read · terms and starting articles
New to a term? Open the trading glossary.
In this article
Decide what the order needs to control
An order is an instruction to your trading provider. A market order prioritizes execution at available prices. A limit order sets a price boundary. A stop order waits for a specified trigger before releasing another order.
Those choices answer a different question from whether a trade is a good idea. First define the setup and its invalidation, then choose an order that matches the required entry or exit. The definitions below describe common behavior; available orders and trigger rules vary by product and provider.
Compare the four common instructions
| Order | What it does | What it does not promise |
|---|---|---|
| Market | Seeks a fill against available liquidity | The last price on your chart |
| Limit | Buys at the limit or lower; sells at the limit or higher | Any fill, even when the chart touches the price |
| Stop-market | Releases a market order after the stop triggers | A fill at the stop price |
| Stop-limit | Releases a limit order after the stop triggers | An exit if price moves beyond the limit |
Investor.gov explains the basic order types for securities. These price and execution distinctions are useful when reading another provider's documentation, but do not establish what that provider supports.
An example: buy a pullback or buy a break
Assume an invented market is quoted at 100.0 bid / 100.2 ask. The bid is what a buyer currently offers; the ask is what a seller requests.
A market buy could fill near 100.2, subject to available quantity and price changes. A buy limit at 99.5 waits for an acceptable lower price. It may remain unfilled if the market rises instead.
A buy stop at 101.0 is a different idea: seek entry after an upward trigger. If the next available ask after triggering is 101.3, a stop-market order may fill there. Replacing it with a stop-limit capped at 101.1 would refuse a fill at 101.3, but could leave the entry unfilled. Neither version makes the breakout more reliable.
These are constructed prices, not live quotes or suggested orders.
For a step-by-step comparison of an ordinary limit and a stop-market order on the same quote path, read stop order vs. limit order. It also separates a plain limit from a stop-limit instruction with two prices.
A candle-close rule needs a completed candle
Suppose a method requires a five-minute close above 101.0. An ordinary buy stop at 101.0 can trigger during those five minutes, even if the candle later closes at 100.5. That order implements a price-touch condition, not the closing condition.
For a closing rule, the candle must finish before the condition is known. Any subsequent execution uses the then-available prices. The closing price in a diagram is not a guaranteed entry fill. This distinction matters in breakout methods.
Compare three orders against the same path
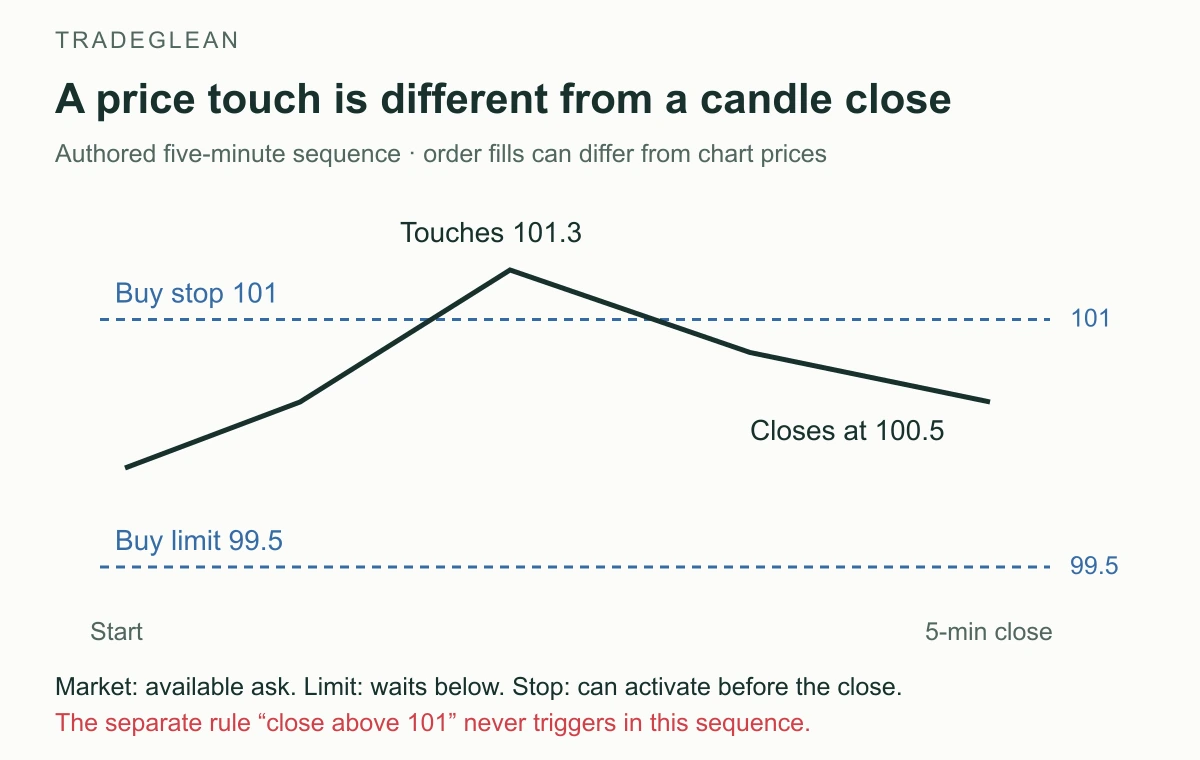
At the initial 100.0 / 100.2 quote, a market buy seeks the available ask. A 99.5 buy limit waits below the market and is never reached in this drawing. A 101 buy stop can activate during the rise. The separate five-minute closing rule fails because the candle ends at 100.5. This is an authored sequence of quotes; a single OHLC candle would not reveal that intrabar order of events.
Choose protection with the failure case in mind
Consider a long position whose protective trigger is 97.0. A sell stop-market could fill at 96.6 after a fast move. A sell stop-limit with a 96.9 floor could remain unfilled while losses continue. FINRA's order guide explains this difference between stop triggers and execution.
Before using an order, establish its trigger basis, active hours, expiry, partial-fill behavior, and whether it closes or opens exposure. For example, a derivatives platform may distinguish last, mark, and index prices. A chart may show a different price from the one that triggers your order.
After a partial exit, the remaining protective quantity must match the remaining position. Otherwise an oversized exit can reverse exposure where the platform permits it. Paired-order cancellation and reduce-only settings are provider-specific, so their behavior must be confirmed in the platform's own documentation.
Continue with spreads, fees, and slippage to calculate what those execution choices cost.
Check your understanding
Your rule requires a completed five-minute close above 101. Price touches 101.3 during the candle, then closes at 100.5. Did the rule trigger? Would an ordinary buy stop at 101 implement the same rule?
Show the explanation
The closing rule did not trigger. A buy stop could have activated before the candle ended, depending on its trigger basis. A touch order and a closing-confirmation rule are different instructions.