Day Trading Basics: Positions, Orders, Costs, and Risk
Understand how an intraday trade works: long and short positions, order types, spreads, trading costs, and the difference between margin and risk.
In brief
- Takeaway
- A day trade opens and closes within one trading day.
- How to use it
- The result depends on direction, quantity, entry, exit, and costs.
- Check first
- Write all five items before an order; a price pattern is only one input.
Before you read · terms and starting articles
New to a term? Open the trading glossary.
In this article
What makes a trade a day trade?
Day trading involves opening and closing a position within the same trading day. The aim is to capture an intraday price move. Holding a position for a short time does not make it low risk: Investor.gov describes the potential for substantial losses over very short periods.
Start by separating four questions: what is being traded, what would trigger the entry, what would end the trade, and how much exposure the position creates. A recognizable chart pattern answers only part of that list.
Long and short describe the direction of exposure
For a simple linear position, a long benefits from a price rise and a short benefits from a decline, before costs. The instrument determines how the position is opened, what one price unit is worth, and whether short exposure is available. Contract multipliers and currency conversion can change the money calculation. CME's trading glossary explains these terms in the context of futures.
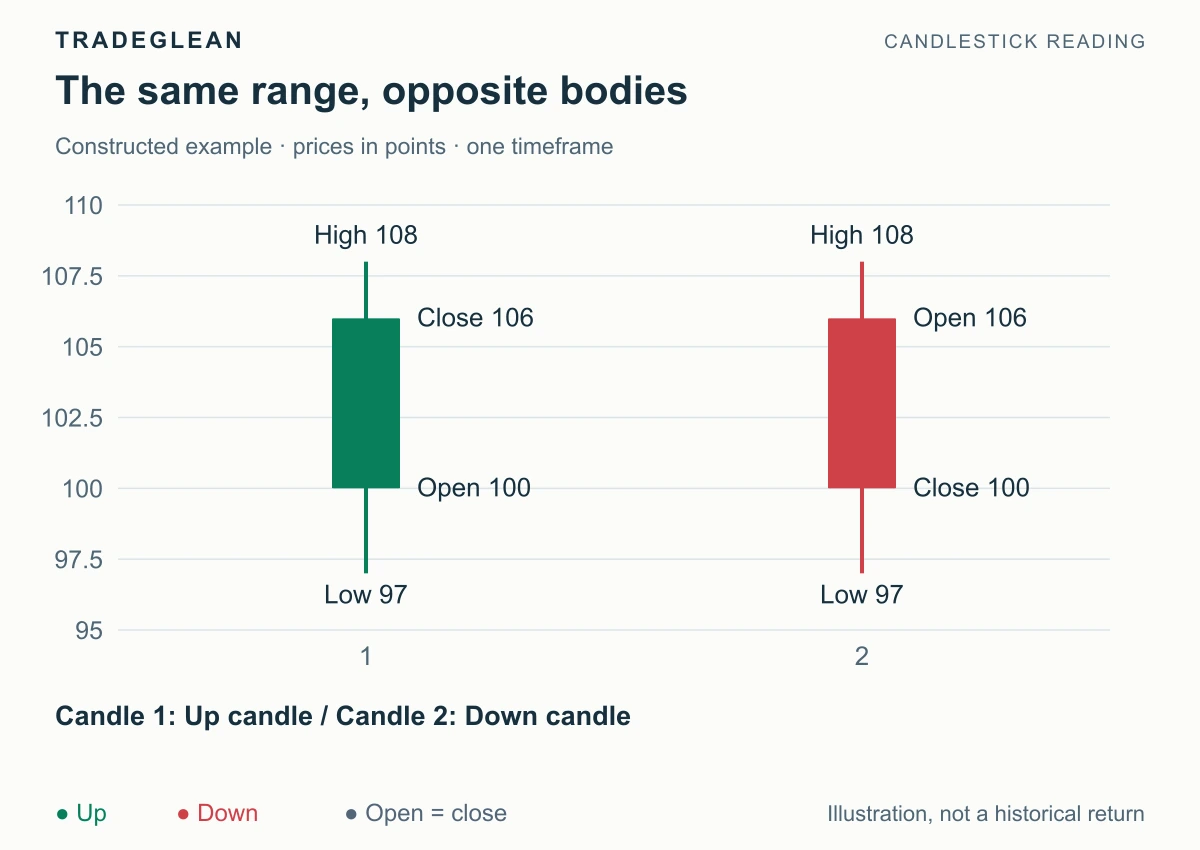
A five-minute candle describes a five-minute interval. It does not specify how long a position must be held. Likewise, an indicator's period setting and a trading session are different concepts. Begin with candle anatomy and timeframes if those labels are unfamiliar.
A simple trade in numbers
Buying 20 units at 100 and selling all 20 at 102 produces a gross gain of 40, if each one-point move is worth one currency unit per unit held. Selling at 98 instead produces a gross loss of 40. Trading costs reduce the first result and increase the second loss. These are invented prices, with no leverage or contract multiplier.
The planned exit price can differ from the actual fill. A stop is an instruction to seek an exit under stated conditions; it is not a guaranteed maximum loss. The position-size example connects this price distance to money at risk.
Follow one position from open to close
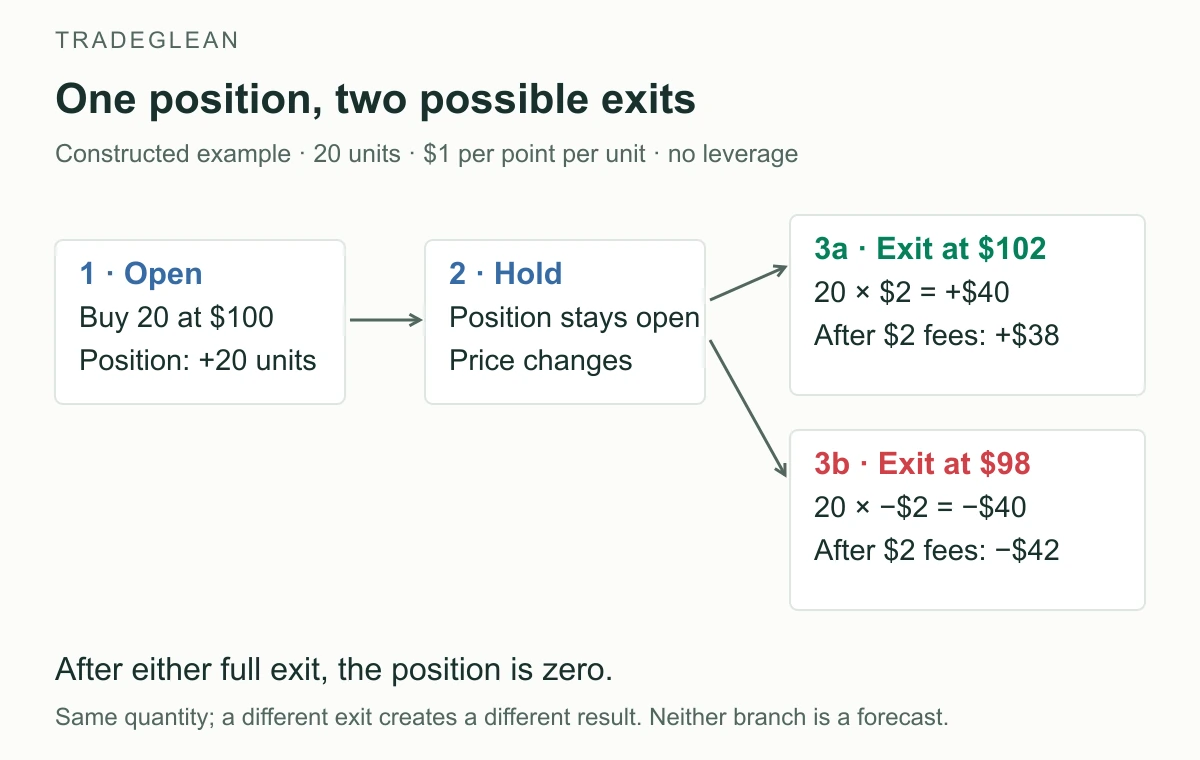
The same 20 units stay open until the exit. At 102 the gross gain is 40; at 98 the gross loss is 40. With 2 of total fees, the net outcomes become +38 and −42. All amounts in this example are US dollars. Neither branch is a forecast; each shows how one exit changes the calculation.
An entry condition and an order are different things
An entry condition describes the event a method requires, such as a completed close above a range. An order tells the provider how to try to execute a transaction.
| Order | Main purpose | Main limitation |
|---|---|---|
| Market | Seek execution at the available price | The fill price can differ from the quote |
| Limit | Set the worst acceptable execution price | The order may not fill |
| Stop-market | Activate a market order when a trigger is reached | The trigger is not a guaranteed fill price |
| Stop-limit | Activate a limit order at a trigger | Price protection can leave the order unfilled |
FINRA's order-type guide explains these distinctions for securities. Order names, trigger prices, availability, and execution rules depend on the product and provider. Check those details before applying a method. A candle close and an intrabar stop trigger can happen at different times.
Costs change the distance a trade must cover
The bid is a buying quote and the ask is a selling quote. Their difference is the spread. A market buy normally pays the available ask; selling normally receives the available bid. See CME's discussion of liquidity and immediacy for how spreads affect execution.
For invented quotes of 100.0 bid / 100.2 ask, buying at 100.2 and immediately selling at an unchanged 100.0 loses 0.2 per unit before additional fees. There was no change in the quoted market, yet crossing the spread had a cost.
Commission, slippage, and any applicable financing also affect the outcome. Compare a strategy's intended price move with the total cost of entering and exiting. Avoid subtracting the spread twice when it is already reflected in the assumed fill prices.
Margin is not the same as money at risk
Margin supports a position; it does not define the maximum possible loss. Exposure, the distance to an exit, the value per price unit, and execution costs belong in the risk calculation. Leverage can increase the effect of price changes on account equity.
For a linear position, a planning calculation is:
Planned risk ≈ quantity × stop distance × value per price unit + estimated costs.
CME's position-size lesson connects stop distance with quantity. This formula is an estimate, not a loss guarantee: an exit can fill beyond the chosen reference. Quantity rounding and minimum order sizes also matter.
Connect the basics to a method
A method needs a market condition, an entry rule, an exit rule, and a risk rule. For example, a trend-pullback method first requires an established trend, while a range breakout starts from a defined boundary. They answer different market conditions.
The signal-to-trade example connects trigger, invalidation, and position size once the mechanics below are familiar. Examples explain methods and their limits; they do not establish profitability.
Continue with market, limit, and stop orders, then see how spreads, fees, and slippage change the result.
When those mechanics are familiar, use the paper-trading practice record to write down a setup, simulated fills, costs, and whether you followed the original rules.
Check your understanding
You buy 20 units at 100 and sell at 102. Each point is worth $1 per unit, and the whole round trip costs $2. What is the net result? What if you sell at 98?
Show the explanation
The gain is 20 × (102 − 100) − 2 = $38. The losing exit gives 20 × (98 − 100) − 2 = −$42. Quantity and costs matter alongside direction; these invented examples assume no leverage.